Netspend

Screenshots
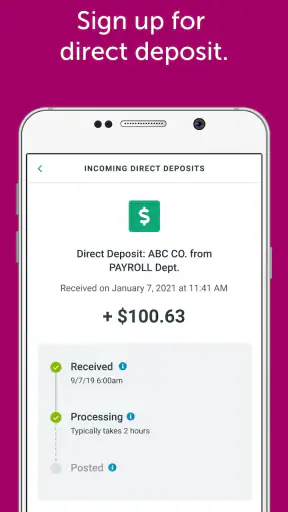
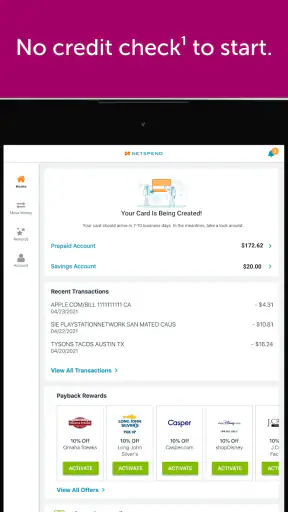
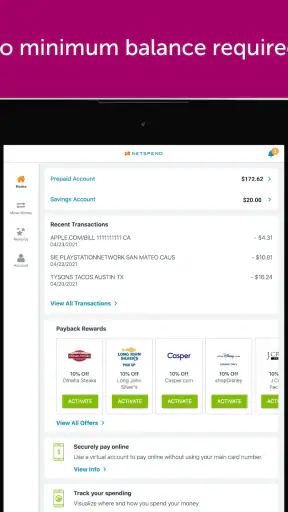
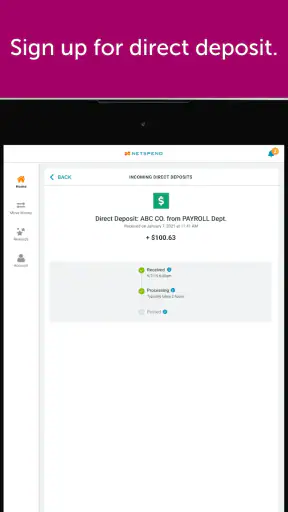
Details
- Rating
- 22.16K reviews
- Version
- 7.0.15
- Developer
- Netspend Corporation
Analysis by Norviv
Managing everyday spending from a phone sounds simple until you need to check a balance quickly, follow a purchase, or decide whether a payment method still fits your routine. Netspend is a finance app from Netspend Corporation that I found most useful when treated as a practical companion to a Netspend account rather than as a complete replacement for every banking tool. It is free, rated for Everyone, and its broad reach—more than ten million installs—suggests that many people use it for regular money tasks rather than occasional curiosity.
My overall impression is straightforward: the app is most appealing to someone who already uses Netspend and wants account information close at hand. It can make routine checking less awkward than relying on a browser, especially when I am away from home or trying to confirm what money is available before paying. At the same time, it is not the kind of finance app I would recommend automatically to somebody looking for a full budgeting platform, investment dashboard, or traditional bank replacement.
How I used Netspend for the everyday money routine
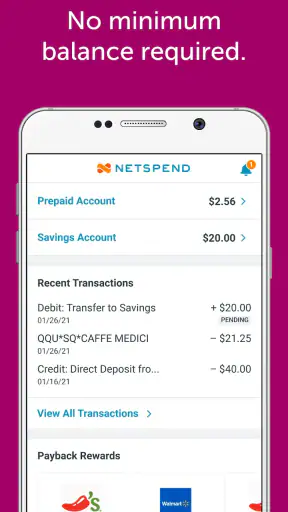
The most sensible baseline workflow starts with a quick check before spending, followed by a review after important purchases. I would open the app before heading to a shop, confirm the available balance, and then return later to make sure the transaction appeared as expected. That habit is more useful than repeatedly opening the app without a purpose, because it turns the phone into a simple checkpoint for decisions I was already making.
For someone paid on a regular schedule, another practical pattern is checking the account at the beginning of a spending period and again before larger bills or planned purchases. This does not create a budget automatically, but it can reduce the common mistake of treating a remembered balance as though it were current. In my experience, the value is less about complex analysis and more about replacing guesswork with a current view.
The app’s store summary, “Your Money, Your Way,” fits that basic role, although I would not read it as a promise of unlimited flexibility. Netspend is still tied to the account and services it supports. The app helps me interact with that setup; it does not turn every financial task into one place.
A realistic example is a busy weekday when I need to buy groceries after work. Instead of estimating whether the account can handle the purchase, I check the balance before entering the store. If I have already made several smaller payments, that quick look is especially useful because those amounts are easy to forget. Afterward, reviewing the activity gives me a second chance to notice whether the purchase has appeared and whether the remaining balance makes sense.
That workflow also reveals an important limitation. A balance check is not the same thing as a full spending plan. I still need my own method for separating rent, food, transport, subscriptions, and discretionary purchases. Netspend can support that process, but I would not depend on it alone if my main goal were category-based budgeting or long-term financial planning.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
What the app is best at for existing users
The clearest strength is convenience. Instead of treating account management as something that must happen at a desktop, I can make it part of ordinary phone habits. That matters for people who want to check money while travelling, waiting in line, or comparing a planned purchase with what is actually available.
It also suits users who prefer short, repeatable interactions. I do not need to turn every visit into a lengthy financial session. A useful routine might be: open the app, check the balance, inspect recent activity when something looks unfamiliar, and close it. Keeping that process consistent makes the app easier to trust because I am using it as a regular reference rather than only opening it when there is a problem.
Netspend has a 4.6 average from roughly one hundred seventy-five thousand ratings, with about twenty-two thousand written reviews. Those figures do not tell me whether every user will have the same experience, but they do show that the app has a substantial audience and a long public history. It was released in May 2011, so this is not a new finance product trying to establish its identity overnight.
Settings and account habits worth checking
When I install a finance app, I pay attention to the settings before relying on it for important decisions. With Netspend, the first useful habit is making sure the account view is configured in a way that matches how often I actually check money. If I only open it around purchases, I want the opening screen and account information to be easy to interpret immediately. If I check more frequently, I want to avoid turning every visit into a hunt through menus.
I also recommend reviewing notification preferences rather than accepting them blindly. Financial alerts can be helpful when they draw attention to account activity, but too many interruptions make it easy to dismiss everything. My preference is to keep alerts that support action and reduce anything that merely creates noise. A notification should prompt me to check something, not become background clutter that I ignore.
Security settings deserve the same attention as convenience settings. I would use the strongest sign-in option available on my device and avoid treating a finance app like a casual social application. I would also inspect the phone’s permission controls and keep the operating system updated. These are not glamorous steps, but they are more valuable than searching for an advanced feature that does not fit my needs.
Another worthwhile habit is checking whether the app is current. The present version is 7.0.15 and it requires iOS or Android version 9 or newer, so compatibility is not an issue for many modern phones. Still, anyone using an older device should confirm that the operating system meets that requirement before planning around the app. A finance workflow is only useful if the app can be installed, opened, and updated reliably.
I would also avoid using a single screenshot as a permanent record of the account. A screenshot captures one moment and can become misleading after another purchase or deposit. For repeatable money management, I prefer checking the live account view when making a decision and keeping separate records only when I genuinely need them for budgeting or documentation.
Faster patterns that save small amounts of time
Experienced use is mostly about reducing unnecessary steps. I would place the app where it is easy to reach, but not in a position where I open it accidentally every few minutes. The goal is a deliberate shortcut: when I need to verify money, I can reach the account quickly, read the important information, and leave without wandering through unrelated screens.
A second shortcut is pairing the app with existing routines. For example, I might check it after receiving income, before a weekly grocery trip, and after a purchase that is larger than usual. This creates useful checkpoints without encouraging constant monitoring. The pattern works because each check has a reason attached to it.
For recurring expenses, I would keep a separate list of expected amounts and dates, then use Netspend to confirm the account position around those events. That division of labor is important. The app can show what is happening with the account, while my own list can show what I expect to happen next. Combining the two is more reliable than asking the app to serve as a calendar, budget, and account viewer at the same time.
When a transaction looks unfamiliar, I would not immediately assume the app is wrong. First I would compare the amount with recent receipts, subscriptions, shared household spending, and purchases made earlier in the day. This simple checking order prevents unnecessary panic and helps distinguish a forgotten payment from a genuinely concerning one. The app is most useful here as a starting point for investigation, not as a substitute for careful review.
Another practical technique is to check the account before committing to a payment rather than after the point of no return. That is particularly helpful for people who use a fixed spending limit. It will not prevent every issue, but it gives me a chance to reconsider a purchase while I still have control over the decision.
Where Netspend reaches its limits
The biggest trade-off is scope. Netspend is a focused finance app, not a universal money command centre. If I wanted investment tracking, detailed net-worth reporting, extensive bill planning, or accounts from several unrelated institutions in one dashboard, I would look at a dedicated budgeting or banking alternative instead.
Traditional bank apps may be a better fit for people who want checking, savings, lending, and broader account services under one established banking relationship. Budgeting apps can be stronger for people who think in categories and want visual reports across multiple accounts. Netspend makes more sense when the account itself is already part of my financial setup and my main need is direct, convenient access.
I would also be cautious about choosing it solely because it is free. Free access removes one barrier, but it does not automatically make an app the best financial tool for every person. The right question is whether Netspend matches the way I receive money, spend money, and monitor the account. Someone who rarely uses a Netspend account may gain little from installing it, while an existing user may find the convenience worthwhile.
The app should not be treated as a complete answer to financial stress either. Seeing a balance can tell me what is available, but it does not explain whether a purchase is wise, whether upcoming obligations are covered, or whether my overall spending is sustainable. Those decisions still require judgment and, in many cases, a separate plan.
There is also a human-factor limitation: convenience can encourage impulsive checking without improving financial control. I get better results when I attach each visit to a clear question—Can I afford this? Did that payment appear? Is the balance consistent with my plan? Without that discipline, the app becomes a quick glance rather than a useful management habit.
Who should use it and who should choose something else
I would recommend Netspend to an existing Netspend customer who wants a simple mobile route to account information and routine money checks. It is also a reasonable choice for someone who prefers a focused app over a large financial dashboard filled with tools they will never use. The free price and Everyone age rating make it approachable for a broad audience, although suitability still depends on the underlying account arrangement.
I would hesitate to recommend it to a person whose main goal is detailed budgeting across several providers. That user may be happier with an app built around categories, goals, and combined account views. I would also point someone toward a conventional bank’s app if they want their primary banking relationship and a wide set of banking services in one place.
Before committing to it as a daily tool, I would ask myself three practical questions. Do I already use Netspend? Do I mainly need quick account access rather than financial analysis? Will I actually check the account at useful moments instead of relying on memory? If the answer to all three is yes, the app has a clear purpose. If not, another finance app may provide a better return on the attention it demands.
My verdict after building a repeatable routine
Netspend works best when I keep the workflow modest: check before meaningful spending, review activity after important transactions, tune notifications so they remain useful, and keep a separate plan for future obligations. Those habits reveal the app’s real value. It is not trying to replace every financial tool; it gives Netspend users a convenient way to stay connected to their account during ordinary days.
Netspend Corporation has maintained the app across a long release history, and its current version shows that it remains an active part of the company’s mobile offering. The large user base and strong average rating make it worth considering, but I would still judge it by fit rather than popularity. A finance app can be well received and still be the wrong choice for someone seeking advanced budgeting or broader banking coverage.
My final recommendation is therefore specific: use it if your financial life already centres on Netspend and you want a quick, repeatable account-checking routine. Keep your expectations realistic, use the settings to reduce distractions, and pair the app with your own spending plan. The best result comes from using Netspend as a reliable daily checkpoint, not pretending it is a complete financial strategy.
Frequently Asked Questions
01What is Netspend, and what can I use it for?
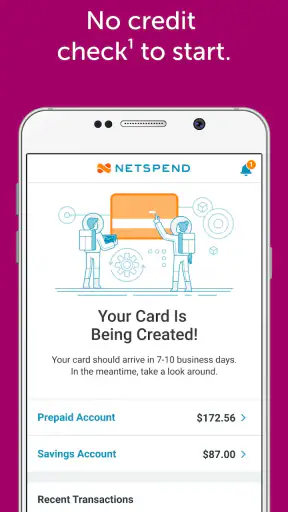
Netspend is a financial service that offers prepaid debit cards and a mobile app for managing everyday spending. After setting up an account, users can typically check their balance, review transactions, receive alerts, deposit money through supported methods, and manage card settings. It is designed for people who want an alternative to a traditional bank account, but availability and features may depend on eligibility, location, and the specific Netspend card selected.
02Is the Netspend app free to download and use?
The Netspend app is generally free to download from the official Android or iOS store, but using the associated card or account may involve fees. Depending on the plan and activity, charges can include monthly service fees, ATM withdrawal fees, cash reload fees, or fees for certain transactions. Before signing up, carefully review the current fee schedule and cardholder agreement because costs can vary by product and may change over time.
03How can I add money to a Netspend account?
Netspend supports several funding options, although the choices available to you may depend on your card, location, and verification status. Users may be able to receive direct deposits, transfer money from an eligible bank account, deposit checks through supported features, or add cash at participating reload locations. Cash reloads may carry a fee, so check the app for nearby locations, processing times, limits, and the exact cost before completing a deposit.
04Is Netspend safe to use for managing money?
Netspend provides standard security tools such as account authentication, transaction monitoring, card controls, and alerts that can help users identify unusual activity. However, no financial app is completely risk-free. Protect your login details, avoid sharing verification codes, use the official app store version, and contact support promptly if your card is lost or a transaction looks unfamiliar. Also remember that prepaid accounts may have different protections and terms than conventional bank accounts.
05What should I know before ordering or activating a Netspend card?
Before ordering a Netspend card, review the applicable fees, spending and withdrawal limits, identity-verification requirements, and funding methods in your area. You may need to provide personal information to open and maintain the account, and some features may require additional verification. Once the card arrives, activation is normally completed through the app or another official channel. Only download Netspend from a trusted store and confirm that the cardholder terms suit your financial needs.


